
The 19th edition of the SACE Export Report, titled “RE-ACT” (RE-Agire), outlines a strategic roadmap for Italian companies facing a fundamentally altered global trade environment. The concept of “re-acting” is not framed as a passive or defensive posture; rather, it calls for proactive, deliberate decision-making under conditions of ongoing uncertainty—turning global complexity into a structural advantage.
From Linear Globalization to Selective Geoeconomic Fragmentation
The global economy has departed from the paradigm of linear globalization focused purely on cost minimization. The contemporary geoeconomic order is shaped by strategic competition between major powers, where tariffs, non-tariff measures (NTBs), technology export controls, and investment screenings are routinely deployed as tools of national security.
Global merchandise trade volume, after demonstrating resilience in 2025 (+3.3%), is expected to experience a natural moderation in 2026 to +2.4%, before settling near its long-term average at +2.7% annually over the 2027–2028 period. Trade flows are relocating along lines of geopolitical alignment (friend-shoring and nearshoring): US imports from China have dropped in favor of Southeast Asia (notably Vietnam) and North America, while Beijing is redirecting its export flows toward broader Asian markets and, temporarily, the European Union to absorb domestic industrial overcapacity.
“This shift does not mark total deglobalization, but rather a transition to a polycentric, selective trade architecture where economic security and strategic autonomy dictate international supply chains.”
Baseline vs. Adverse Scenario: Factoring in Geopolitical Shocks
SACE’s macroeconomic models evaluate the potential escalation of Middle Eastern conflict, specifically regarding operational disruptions in the Strait of Hormuz:
- Baseline Scenario (40% Probability): Assumes a gradual, progressive normalization of shipping traffic in the Strait of Hormuz during the final quarter of 2026. Under this outlook, Italian merchandise exports will grow by 2.0% in value in 2026 (reaching €656 billion), accelerating to +2.5% in 2027 (€673 billion) and +2.8% in 2028 (€691 billion). This trajectory supports the strategic target of achieving €700 billion in total exports by 2028.
- Adverse Scenario (Prolonged Conflict): Should maritime blockades in the Persian Gulf persist for approximately six months, global energy markets would experience a severe supply shock, driving crude oil (Brent) above $125/barrel with peaks exceeding $160/barrel. This would reignite global inflation (to 4.1%) and contract Italian export volumes in 2026 (-1.8%) and 2027 (-3.1%). However, due to price-driven effects (Average Unit Values), nominal export value would still register +1.2% in 2026 and +2.1% in 2027, before rebounding by +4.9% in 2028.
Services Export: The Intangible Powerhouse of Italian Industry
Italian exports of services reached €149 billion in 2025 (+3.9%) and are projected to grow by 3.5% in 2026 (€154 billion) and 4.2% on average across 2027–2028 (climbing to €167 billion).
The “Servitization” of Manufacturing
The expansion of services exports is closely linked to their integration into manufacturing. Italy boasts a higher service-value component embedded within its manufactured exports than the EU and OECD averages. Intangible inputs—such as research and development, industrial design, predictive maintenance, digital marketing, and post-sales technical support—now represent core value drivers for physical products.
Inbound Tourism and Per-Capita Purchasing Power
Tourism remains the largest single component of services exports, accounting for 38% of total service receipts (€57 billion in 2025, +4.6%). In 2025, Italy welcomed 92 million international visitors (+4%). While total expenditure is led by European (notably German) and American travelers, per-capita spending analysis reveals significant variation:
- Japanese Visitors: ~€2,400 per capita;
- Australian Visitors: ~€1,800 per capita;
- US & Russian Visitors: ~€1,600 per capita;
- European Union Average: ~€500 per capita (reflecting shorter, higher-frequency stays).

Geographic Horizons: Target Markets and “Intelligent Diversification”
Currently, 45% of active Italian exporters operate in only one foreign market, indicating underutilized potential for international expansion. Although Italy maintains a high extra-EU export share (48.2% of total exports in 2025), approximately 30% of Italian companies state they are actively seeking entry into new geographic markets.
SACE has identified 16 Strategic High-Potential Markets that combine robust economic growth, industrial modernization programs, and manageable risk profiles: China, Turkey, United Arab Emirates, Saudi Arabia, Mexico, South Korea, Brazil, India, Singapore, Morocco, Egypt, Thailand, Malaysia, Vietnam, Kazakhstan, and the Philippines. Italian exports to these 16 markets are projected to grow by 1.4% in 2026 (offsetting temporary contractions in the Gulf) and by 4.4% annually in 2027–2028, reaching €92 billion.
Regional Market Analysis
North America: Absorbing Tariff Surges
In the United States, anticipation of new import tariffs led to a pre-emptive buying surge (front-loading) in 2025 (+7.2% overall, with pharmaceutical exports from Lazio and Tuscany surging over +40%). In 2026, growth will stabilize at +1.9% (with US-bound goods growing +1.1%), before accelerating to +3.3% in 2027–2028. US demand focuses on capital machinery (+1.5%), industrial automation, defense components, and high-end consumer goods.
Advanced Europe
Italy’s top four traditional export destinations (Germany, US, France, Spain) absorbed €245 billion in 2025 (38% of total exports).
- Germany: Following economic stagnation, German demand is expected to recover moderately (+1.1% in 2026; +2.4% in 2027–2028), supported by public expenditure in energy grid modernization, defense, and a €500 billion climate/infrastructure fund.
- France: The “France 2030” investment framework drives demand for Italian specialized machinery (+0.8%), electrical equipment (+2,4%), and premium agri-food. Total exports to France will expand by +1.3% in 2026.
- Spain: Outperforming Eurozone averages, Spanish demand will grow by +3.3% in 2026, boosted by Next Generation EU funds and renewable energy installations.
Asia-Pacific: The Dynamic Engine
The Asia-Pacific region is projected to expand by +3.5% in 2026 and +3.4% annually in 2027–2028.
- China: Under its 15th Five-Year Plan (2026–2030), China is prioritizing AI, advanced semiconductors, and domestic consumer upgrade programs. Italian exports are forecast to rebound by +5.7% in 2026.
- India: Accelerated by the “Production Linked Incentive” (PLI) schemes, Italian exports will grow +3.5% in 2026 and +6.2% by 2028, aided by the EU-India Free Trade Agreement.
- Vietnam & Indonesia: Vietnam (+3.7% in 2026, +5.4% in 2027–28) benefits from tariff eliminations under the EVFTA agreement. Indonesia (+5.0% in 2026) requires Italian industrial machinery to support domestic mineral processing mandates.
Sub-Saharan Africa and the Mattei Plan
Sub-Saharan Africa shows strengthening demand (+3.7% in 2026), driven by the implementation of Italy’s Piano Mattei. Exports to the 18 priority nations targeted by the initiative (worth €14.4 billion in 2025) will see strong performance in Angola (+15.8% in 2026) for energy and food processing, and Tanzania (+11.5%) for port and rail developments.
Trade Policy: Non-Tariff Barriers, US Duties, and New EU FTAs
International commerce is undergoing a structural shift in regulatory architecture, as non-tariff measures increasingly replace traditional customs duties as the primary friction point in global trade.
The Proliferation of Non-Tariff Measures (NTBs)
According to UNCTAD data cited by SACE, for 88% of countries worldwide, the cost impact of non-tariff measures now exceeds that of traditional tariffs. NTBs include technical regulations, import licensing, sanitary requirements, and environmental compliance. Unnotified technical regulations function as an implicit tariff of 28%, whereas international regulatory harmonization could reduce trade costs by nearly 20%.
The US Tariff Landscape: From IEEPA to Section 122
The transatlantic trade policy environment experienced volatility between 2025 and 2026:
- April 2, 2025 (“Liberation Day”): The US administration announced broad tariff increases using the International Emergency Economic Powers Act (IEEPA), raising effective average US tariffs from 2.4% to a peak of nearly 23% by May 2025.
- February 20, 2026: The US Supreme Court (SCOTUS) ruled that IEEPA tariffs were unconstitutional without explicit Congressional approval, leading Customs and Border Protection (CBP) to open refund procedures for an estimated $150 billion in collected duties.
- US Policy Response (Section 122): The White House responded by imposing a 10% temporary duty under Section 122 of the Trade Act of 1974 (addressing balance-of-payment imbalances, capped at 150 days through July 24, 2026, pending Congressional action).
- Impact on Italian Exporters: Trade uncertainty reduced Italian manufacturing export growth to the US by approximately 1 percentage point (~€1.5 billion in unrealized expansion), with an estimated potential exposure of up to €11.5 billion.
EU Free Trade Agreements as Industrial Instruments
In response to global fragmentation, the European Union has accelerated the negotiation and implementation of modern bilateral Free Trade Agreements (FTAs):
Supply Chain Security: Critical Raw Materials & Water Infrastructure
A core finding of the SACE report is that export competitiveness is directly dependent on managing strategic import supply chains.
The EU Critical Raw Materials Act (CRMA) and Italy’s Import Exposure
The EU Critical Raw Materials Act (CRMA) identifies 34 critical and 17 strategic raw materials. It sets quantitative benchmarks for 2030: at least 10% domestic EU extraction, 40% processing, 25% recycling, and a maximum 65% import dependency on any single third country for any strategic material.
Italy enacted these guidelines via Decree-Law 84/2024 (Critical Raw Materials Decree). Given limited domestic mining potential, Italy’s national policy focuses on industrial recycling, circular economy processes, and downstream processing.
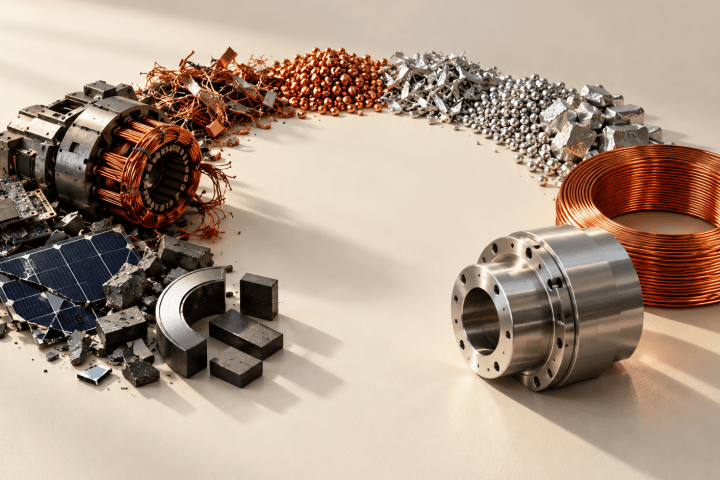
Four materials (Copper, Aluminum, Platinum Group Metals, Nickel) account for 91% of the total value of Italian strategic raw material imports (~€20 billion annually). Including Silicon, Titanium, and Manganese brings the total to 99%, forming the material base for metallurgy, automotive, machinery, electronics, and aerospace.
The Role of Export Credit Agencies in SACE
With 16% of global critical raw material trade subject to export restrictions, SACE utilizes financial risk-sharing, long-term off-take guarantees, and blended finance structures to secure input availability for domestic industrial supply chains.
Water Infrastructure: Italian Engineering Solutions
Global water scarcity costs the world economy over $307 billion annually, with 72% of freshwater withdrawals absorbed by agriculture, 16% by domestic uses, and 12% by industry.
- Central Asia: Regions such as Kazakhstan (60% system loss rate), Uzbekistan (40% canal transportation loss), and Turkmenistan face acute hydrological deficits.
- Western Balkans: The EU’s Western Balkans Investment Framework (WBIF) has mobilized €1.5 billion for water purification and municipal sewer upgrades.
- Italian Industrial Footprint: Italian engineering firms hold strong global market positions in industrial wastewater treatment, remineralization, desalination, and precision agricultural irrigation.
Strategic Industrial Value Chains & Sectoral Forecasts
Global industrial production is defined by international specialization. In Italy, 41% of total manufacturing output is directly or indirectly activated by participation in global value chains (GVCs), representing an increase of 10 percentage points over the past decade.
Italy’s strategic industrial value chains generate over half of national industrial turnover and exhibit an average export propensity (32%) more than double that of the wider economy (15%).
Sectoral Export Forecasts (2026–2028)
1. Agri-food & Consumer Goods
- Agri-food (+3.1% in 2026): Led by raw agricultural produce (+3.4%) and processed food and beverages (+2.9%). Competitiveness relies on Agritech integration (satellite irrigation monitoring via aerospace technology) and premium branding.
- Consumer Goods (+2.5% in 2026): Growth in 2026 is driven by “other consumer goods” (+5.2%), notably exports of unwrought gold and precious metals to Switzerland (refining hub), Turkey, and China as safe-haven assets. Leather goods and fashion remain soft in 2026 due to Middle Eastern headwinds, but are projected to recover in 2027–2028 (+2.3%).
2. Intermediate Goods
- Chemicals & Pharmaceuticals (+1.2% in 2026; +3.0% in 2027–28): Following high growth in 2025 (driven by GLP-1 weight-loss therapeutics and US inventory building), pharma exports are stabilizing while applying AI tools to accelerate drug discovery.
- Metals (+2.1% in 2026; +2.8% in 2027–28): Supported by European infrastructure and defense spending. The implementation of the CBAM framework protects European steel and metal fabricators from high-carbon imports, despite raising raw material import costs.
3. Investment Goods (Capital Goods)
- Specialized Machinery (+1.4% in 2026; +3.1% in 2027–28): Remains Italy’s single largest export sector. Custom industrial automation, packaging systems, and energy-efficient machine tools drive the recovery.
- Electrical Equipment (+1.6% in 2026; +2.7% in 2027–28): Driven by global grid electrification, renewable energy installations, and data center buildouts for AI infrastructure.
- Transport Equipment (+0.6% in 2026; +2.8% in 2027–28): A transition year reflecting European automotive challenges, compensated by shipbuilding, luxury yachting (superyachts), and aerospace technologies.
Strategic Action Plan for International Business: The “SACE50” Framework
To support corporate expansion in a more selective global environment, SACE’s Strategic Plan 2026–2028 (SACE50) establishes three operational priorities:
- Targeted Market Penetration: Reallocating export capacity toward the 16 High-Potential Markets, supported by sovereign credit insurance, political risk protection, and diplomatic channels.
- Supply Chain Security: Utilizing new-generation EU trade agreements (Mercosur, India, Australia) and blended finance to secure stable access to critical raw materials and energy inputs.
- Multi-Chain Industrial Integration: Encouraging SMEs to pivot across related industrial supply chains. A primary example is the Italian automotive component sector, where sub-suppliers are reallocating production capacity toward high-growth, high-margin sectors such as defense and aerospace.
The SACE 2026 Export Report highlights that while geopolitical volatility continues to shape international commerce, Italian manufacturing retains the technological flexibility, structural diversification, and institutional backing necessary to sustain its global expansion.
To help international readers navigate the institutional framework governing Italian international trade, several key entities and terms referenced in this analysis require context:
- SACE: Italy’s official Export Credit Agency (ECA), operating under the Italian Ministry of Economy and Finance (MEF) and controlled by Cassa Depositi e Prestiti (CDP). SACE manages sovereign guarantees, credit insurance, and investment protection for Italian exporters.
- CDP (Cassa Depositi e Prestiti): Italy’s National Promotional Institution and sovereign investment bank.
- Piano Mattei (Mattei Plan): The Italian government’s strategic foreign policy initiative aimed at building long-term, non-predatory economic, energy, and industrial partnerships across Africa.
- Sistema Italia (“System Italy”): The coordinated institutional network comprising the Ministry of Foreign Affairs (MAECI/Farnesina), SACE, SIMEST, the Italian Trade Agency (ITA/ICE), and diplomatic channels that jointly support Italian corporate expansion abroad.
- Industrial Districts (Distretti Industriali): Specialized geographic clusters of highly interconnected small and medium-sized enterprises (SMEs) that characterize Italy’s manufacturing model (e.g., packaging in Emilia-Romagna, eyewear in Veneto, textiles in Biella/Prato).
- CBAM (Carbon Border Adjustment Mechanism): The European Union’s environmental tariff on carbon-intensive imports (e.g., steel, aluminum) designed to prevent carbon leakage and ensure fair competition.